By one account, the biggest crypto exchange on the planet came close to running legally within the European Union. Then the head of the European Central Bank intervened, and the door closed.
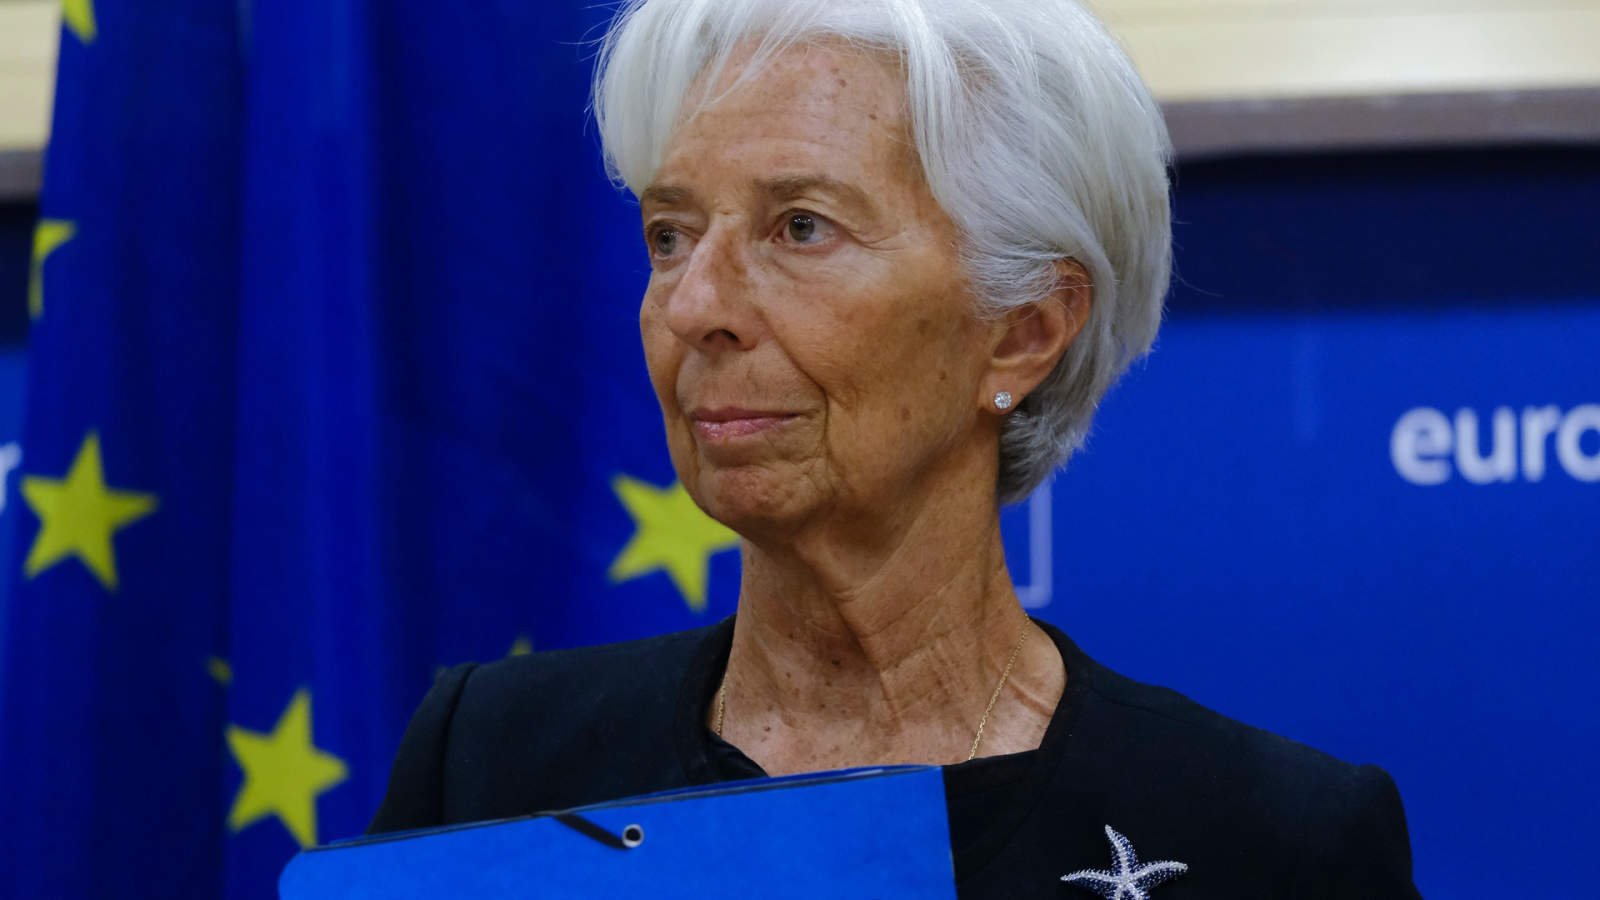
That is the allegation in a Wall Street Journal report published Thursday, which said Christine Lagarde blocked Binance from gaining a foothold in the trading bloc. Interviews with officials were the paper’s sourcing.
“Lagarde wanted to keep the controversial crypto exchange, which pleaded guilty to financial-crime violations in the U.S., out of the European Union,” the report said.
The license Binance doesn’t have
European law leaves little room for interpretation on this point. A MiCA license is required for local Crypto-Asset Service Providers to operate. Binance holds no such license.
June saw the exchange pull its MiCA application in Greece. Its statement at the time said it was still working to pursue MiCA authorization in another EU member state.
For anyone trading from inside the bloc, then, nothing has shifted in practical terms. What the report contributes is a name and a motive behind the wall.
Lagarde’s position on Bitcoin isn’t new
For anyone tracking her public remarks, none of this is a surprise. In 2021, Lagarde described Bitcoin as “a highly speculative asset” used for money laundering. Her criticism extended to cryptocurrencies generally, and she said central banks would never hold bitcoin.
That is a stance on the record for five years now, not an abrupt pivot. The Journal’s story lands less as a revelation than as confirmation that a stated view hardened into an operational one.
The stablecoin worry is the more interesting part
Tucked into the report is a motive with no connection to Binance’s criminal record. According to the paper, citing various interviews, Lagarde feared Binance would entrench the dominance of dollar-based stablecoins across Europe rather than give euro alternatives room to grow.
That reasoning is about currency sovereignty, not consumer protection. And it lines up with the rest of the ECB’s agenda.
Binance is the world's biggest crypto exchange, and billions of dollars in stablecoins change hands on its platform every day. License that volume into the euro area and the approval covers more than an exchange — it covers a distribution channel for dollars.
The digital euro is the other half of this
Central bank digital currencies occupy a different category in Lagarde’s thinking than crypto does. A CBDC is a digital form of fiat money, like the US dollar or euro, and countries worldwide sit at varying stages of researching and issuing them.
Under Lagarde, the EU is pushing quickly toward a digital euro. She has called it key to Europe’s financial autonomy, while training her criticism on privately issued stablecoins.
Bitcoiners and other voices in the crypto industry have attacked CBDCs over surveillance, arguing the tools could be turned on citizens. The objection carries political weight in the US, where President Donald Trump signed an executive order banning CBDCs when he took office.
The result is two jurisdictions running opposite experiments simultaneously. One is constructing the thing. The other has made it illegal.
Binance’s record makes the block easy to defend
Whatever the merits of the stablecoin argument, the exchange gave regulators a ready-made justification. In 2023, Binance and its CEO, Chanpeng Zhao, pleaded guilty to anti-money-laundering violations and paid a record $4.3 billion fine.
In a licensing meeting, a record fine is difficult to talk around. It hands any official inclined to refuse a rationale that spares them from explaining currency policy to the public.
Traders inside the EU waiting for Binance to walk in through the front door should track which member state receives its next MiCA filing — and how fast that regulator acts. The second answer will be more revealing than the first.