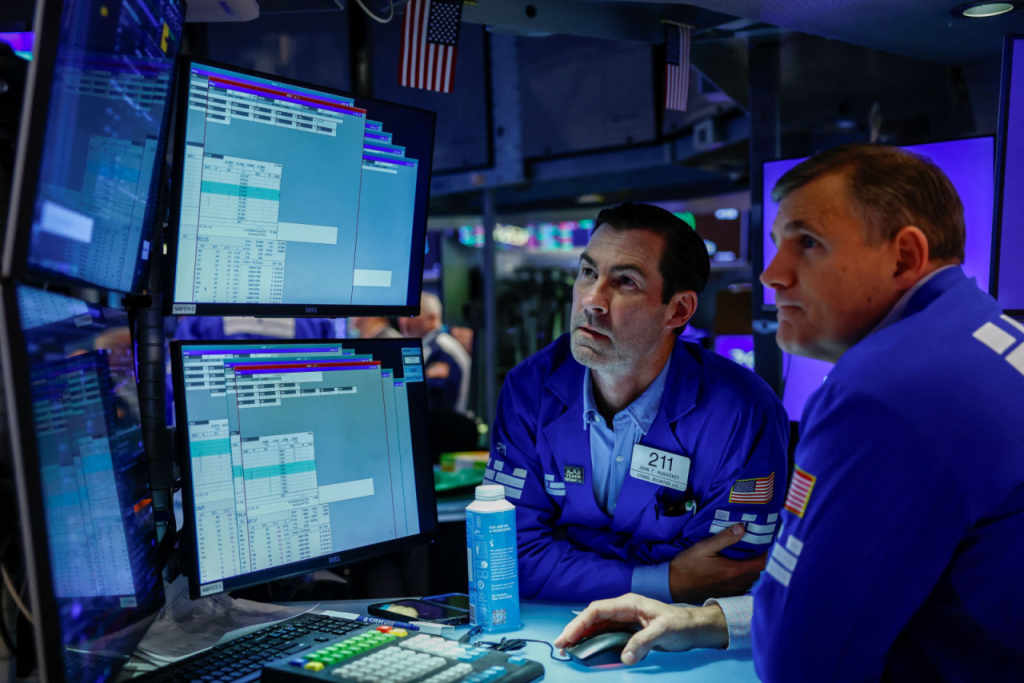
At the start of this month, the 10-year Treasury yield sat just under 4.8%. By Friday it had climbed to 5.23%, a level not seen since 2007.
For the benchmark that helps determine mortgage rates, that is a sizable jump. Sticky inflation is the obvious explanation, but it only tells part of the story.
The easy answer is inflation
Begin with the view most investors held going in. Inflation has not eased the way markets had hoped, so traders are now betting on further tightening from the Federal Reserve.
According to the CME FedWatch tool, trading in Fed funds futures points to a 64% chance of a rate hike in October. Households are uneasy as well. In the University of Michigan’s consumer sentiment index, year-ahead inflation expectations rose to 4.6% in September from 4% in August, the highest reading since June.
A quick primer for anyone who doesn’t track the bond market: prices and yields move in opposite directions. A yield rising this quickly means bond prices are dropping.
One strategist thinks supply matters more
Thierry Wizman, global FX and rates strategist at Macquarie Group, believes inflation isn’t the main driver.
“I think this year it has more to do with the bond issuance than the inflation story,” Wizman said.
In his view, yields at these levels are not unusual on their own, especially since they aren’t accompanied by extreme inflation expectations or a Fed that is tightening aggressively.
“We don’t have a Federal Reserve that’s tightening aggressively, so a lot of things look pretty normal. The thing that’s abnormal is that we’re in the midst of a very strong investment cycle,” he said.
Washington and Big Tech are both borrowing
The market is absorbing demand from two major borrowers at the same time. The federal government is selling debt to finance a large deficit, while corporations are borrowing heavily to fund artificial intelligence infrastructure.
According to Wizman, that pairing has lifted bond supply enough to push yields higher. Corporate debt tied to AI is now vying with Treasuries for the same pool of investor money.
The figures stand out. Vanguard estimates that Alphabet, Amazon, Meta Platforms, Microsoft and Oracle issued about $132 billion of debt through July. From 2020 to 2024, the same companies averaged roughly $35 billion annually.
The borrowing isn’t limited to those five giants. As data center operators, chipmakers and utilities take on debt to finance the buildout, broader AI-related issuance could total $300 billion to $570 billion this year.
Why stock investors should care
Rising yields affect more than homebuyers. They can weigh on equities by lifting corporate borrowing costs and by making bonds more attractive to income-seeking investors.
The result is an uncomfortable cycle. The same AI spending that has fueled so much market excitement is also adding to the bond supply that drives yields higher and pressures stocks.
Don’t expect relief soon
Wizman expects the capital-spending plans of hyperscalers and their suppliers to keep bond issuance high for the rest of this year and into next year.
Would-be buyers holding out for lower mortgage rates won’t find comfort in his outlook: “So these yields could go higher,” he said.