For 15 years, Kraken’s business was running a crypto exchange. Over just the past two, its parent company has spent billions of dollars on acquisitions: a futures brokerage, a derivatives exchange and, if its co-CEO is right, soon a European bank as well.
Payward, the Wyoming-based firm that owns Kraken, doesn’t want to be known only as a place where people trade coins. Its aim is to run the infrastructure underneath trading, banking, asset management and business services, with all of it sitting on shared systems.
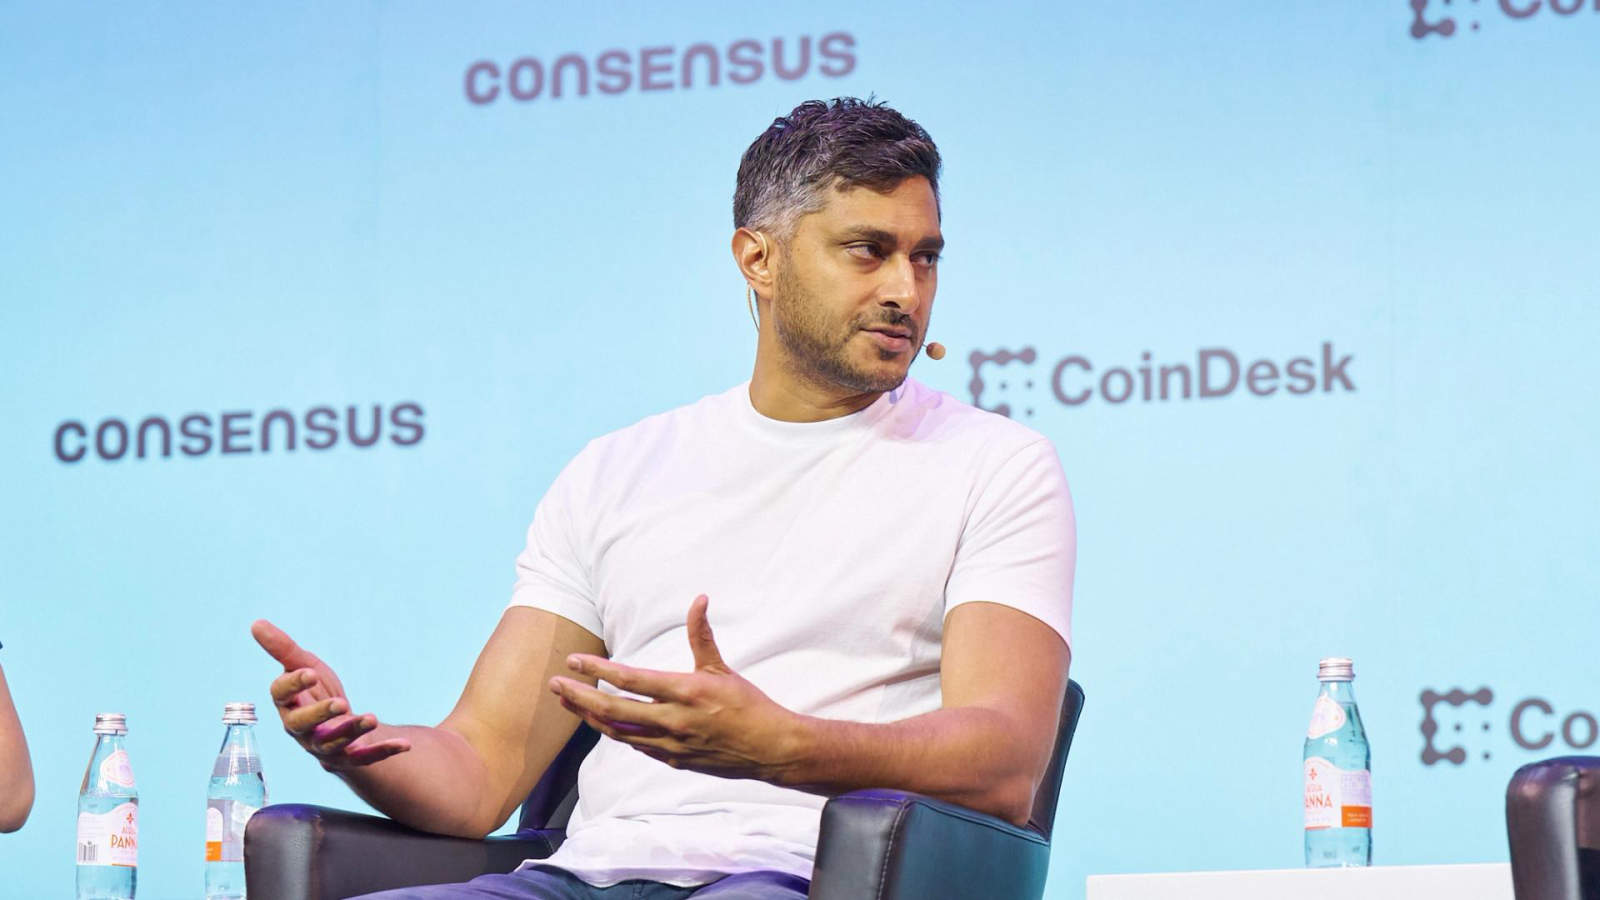
“We’re not a holding company,” co-CEO Arjun Sethi said. “It’s one platform, one balance sheet, one regulatory stack.”
The one ledger pitch
Sethi’s strategy is built around an idea he calls “one ledger.” The concept is that money and assets should be able to move from one product to another without going through the long chain of intermediaries that most of traditional finance still depends on.
His complaints about the legacy system are familiar ones, and they’re difficult to dispute. Securities take time to settle. Markets shut overnight and on weekends. Banks, brokers, custodians and clearing houses all keep their own records, and those records have to be reconciled with each other.
Sethi said every one of those handoffs brings in another intermediary, another delay and another fee. He sees blockchain systems as the way out, because they let a single asset work as an investment, as collateral and as a programmable instrument on the same infrastructure.
That’s the theory. The more revealing part is how Payward is paying to make it real.
Buying what would take years to build
Payward develops some of these pieces itself. Others it simply buys.
To set up a U.S. futures brokerage, the company paid $1.5 billion for NinjaTrader, which brought over its technology and regulatory permissions. Sethi said building the same thing from scratch would have been expensive and slow.
A $550 million deal for Bitnomial came next. It added regulated derivatives infrastructure in the form of an exchange, a clearinghouse and a futures brokerage.
A bank is the next item. Sethi said the firm is “about to buy a bank in Europe” but declined to name the target. In July, Bloomberg reported that Payward was planning to acquire a Lithuanian bank as part of its expansion in Europe.
Sethi said Payward doesn’t keep a shopping list and doesn’t take general pitches from bankers. Instead, it puts potential targets through a quantitative framework built around two questions: does the deal fill an infrastructure gap, and does it give customers something they actually want?
Some things can’t be bought
There’s an irony here. Some of Payward’s most important moves are partnerships with the same incumbents that blockchain was once expected to replace.
This month, Nasdaq agreed to invest $100 million in Payward, and the two are expanding their joint work on Nasdaq Equity Tokens and market surveillance technology. They expect the tokens to launch in the second quarter of 2027. Payward will handle distribution, trading and post-trade infrastructure.
The London Stock Exchange has also partnered with Payward to look into tokenized public equities. Pending regulatory approval, the exchange plans to list xStocks, which are tokenized representations of publicly traded shares, on its upcoming LSE 24 venue in 2027.
Sethi didn’t claim that blockchain makes these institutions obsolete. “Trust is their currency,” he said. In his view, Payward can add to established exchanges’ listing and regulatory infrastructure rather than push it aside.
That’s a far humbler position than crypto executives used to take, and it’s also a practical one. A century of market credibility isn’t something you can acquire.
Four pillars, 6.6 million accounts
Payward’s plan rests on four pillars: trading through Kraken, banking, asset management and Payward Services, which is its business-to-business infrastructure arm.
According to Sethi, the foundation is Kraken’s roughly 6.6 million funded accounts. Together they hold between $40 billion and $50 billion in assets across more than 190 countries and territories.
On top of that customer base, Payward is adding cards, lending, derivatives and tokenized equities. It’s also adding products that let customers borrow against their holdings or put them to work in decentralized-finance applications. Kraken Financial, the company’s Wyoming-chartered special-purpose depository institution, is part of the stack too.
A smaller exchange with a different bet
Payward isn’t the only crypto company trying to build an all-in-one financial platform. Coinbase is working on an “Everything Exchange” that covers crypto, stocks, derivatives and prediction markets. Binance is bringing trading, payments, investing and yield products together on one platform.
By raw exchange volume, Kraken is the smaller player. It averaged about $1.1 billion in daily spot trading over the first four months of 2026. For comparison, Binance held 38.7% of top-10 centralized-exchange spot volume in the second quarter, and Coinbase reported an 8.6% share of overall crypto trading volume in the first quarter.
Architect Partners, an investment bank focused on digital assets, argues that Payward is playing a different game from Coinbase. Payward isn’t trying to fit every product into one Kraken-branded app. Instead, it’s building infrastructure that can run multiple brands and can be rented out to other financial companies.
“Payward appears to be choosing a different aggregation layer: the regulated infrastructure stack that can power financial products across multiple brands, customer segments, and partner channels,” Architect Partners said.
“In our view, Payward is helping define the next evolution beyond the ‘Everything Exchange’: an ‘Everything Financial Infrastructure’ model.”
Selling Kraken’s plumbing to everyone else
Renting out that infrastructure is the job of Payward Services, and it may say more about the overall strategy than anything else.
The unit grew out of systems Payward had already built for its own use: custody, liquidity, compliance, risk management, payments and settlement. It now offers those systems to banks, fintech companies, brokerages and crypto platforms through one shared set of APIs and a single integration.
Sethi said at least 25 companies are building products on the service and are expected to launch this year. Hyperliquid is one of the partners.
The appeal is that this kind of distribution doesn’t depend on people downloading Kraken. “Payward’s model can work even when the end customer never interacts with Kraken directly,” Architect Partners said.
It gives Payward a revenue stream beyond trading fees. It also puts the company in a crowded market, since plenty of crypto firms are already pitching infrastructure to banks and fintechs.
Asset management, tokenized
Payward is taking the same approach with investment products. It has offered custody, staking and yield for years, and it’s now turning those into a formal asset-management platform that can bring in more managers, strategies and asset classes.
Payward isn’t going after conventional investment mandates. It wants to be the execution and distribution layer for structured products, tokenized equities, credit and multi-asset strategies, while the assets themselves stay on its platform.
Tokenized equities are the first priority. Structured products that can be broken into smaller units and sold globally will follow. Payward recently partnered with Bitwise on an institutional investment product and expects to add more managers and strategies.
Sethi said these would look like traditional asset management products from the outside. Underneath, they would be tokenized and run on Payward’s rails, which would lower costs and reduce counterparty exposure.
Not waiting on Washington
Sethi isn’t worried about stalled U.S. crypto legislation. The company supported the Clarity Act and has spent years educating policymakers, but he said laws formalize industries rather than create them.
“Bitcoin has been around for 17 years without a market-structure bill,” he said. “Rights come first and laws come later and legislation comes downstream.”
The IPO can wait
All of this is happening as Payward moves toward an eventual public listing. Even so, Sethi said the company isn’t relying on an IPO to fund any of it.
Payward filed confidentially for an IPO in November 2025. Earlier this month, it was reported that the company doesn’t plan to go public before the second quarter of 2027 at the earliest. Sethi wouldn’t discuss timing beyond what’s already public. He said the company is still profitable, revenue continues to grow, and a listing will happen when the timing is right for the business, its shareholders and regulators.
Sethi said Payward doesn’t need outside capital to operate and can fund its investments from its own balance sheet. He said recent fundraising has been about bringing in strategic partners such as Citadel Securities and Nasdaq, whose expertise can help extend the platform.
The financials give that claim some support. Payward reported $508 million in adjusted revenue for the second quarter of 2026, a 17% increase from the same period a year earlier.
Sethi’s ultimate goal is to give ordinary people the same financial infrastructure used by firms like Jump Trading and Jane Street. Whether that’s achievable depends on three things: the European bank deal closing, the 25 partner launches shipping and the Nasdaq tokens meeting their 2027 target. Sethi summed up the whole plan in four words: “Fix money, fix the world.”